
This is particularly important for British expatriates who continue to use a financial adviser based in the UK.
Since Brexit, being authorised by the UK's Financial Conduct Authority (FCA) does not, by itself, give a UK financial adviser the right to provide regulated investment services to residents of France.
So how can you check whether an adviser is properly authorised? And what protections should you expect when receiving financial advice in France?
This guide explains the main issues.
Quick answer: who can give financial advice to expats in France?
For investment advice, a Conseiller en Investissements Financiers (CIF) must be registered with ORIAS and be a member of a professional association approved by the Autorité des Marchés Financiers (AMF).
The AMF states that CIFs must meet requirements relating to professional competence, good repute, and possess professional indemnity insurance.
For British expatriates, the important point is simple:
Do not assume that a UK authorisation automatically covers financial advice provided to you once you live in France. Check the adviser's French or EU regulatory permissions.
You can verify a French intermediary directly through the official ORIAS register.
Why Brexit changed financial advice for British expats
Before Brexit, authorised UK financial businesses could use European "passporting" arrangements to provide certain services across the European Economic Area without obtaining separate authorisation in each country.
The end of the Brexit transition period on 31 December 2020 fundamentally changed that position for UK firms.
The United Kingdom became a "third country" for EU financial-services regulation. UK authorisation therefore no longer provided the same automatic passporting rights into France and other EU member states.
This matters particularly where an expatriate has retained:
- UK personal pensions
- SIPPs
- investment portfolios
- ISAs
- offshore investments
- discretionary investment arrangements
The fact that an adviser originally advised you while you lived in Britain does not automatically mean that the same regulatory position continues after you become resident in France.
What about "reverse solicitation"?
This is one of the most misunderstood areas of cross-border financial advice.
You may hear the argument that a UK adviser can continue servicing a French-resident client because the client approached the adviser rather than the other way around.
This is commonly referred to as reverse solicitation.
Article 42 of MiFID II provides a limited exemption when an EU-based client initiates an investment service with a third-country firm entirely on their "own exclusive initiative".
But that exemption is much narrower than is sometimes suggested.
ESMA has specifically warned firms against attempting to circumvent the rules through contractual clauses, disclaimers or online statements declaring that the client initiated the relationship.
If the third-country firm solicits, advertises or promotes investment services to clients within the EU, the service should not simply be treated as having arisen through the client's exclusive initiative.
ESMA also makes clear that the exemption does not provide an unrestricted right to market new categories of investments or services to that client.
In practical terms, reverse solicitation should not be treated as a blanket regulatory passport for an ongoing financial-advice relationship.
How financial advisers are regulated in France
France has no single label covering every type of financial advice.
The regulatory position depends partly upon what the adviser is recommending and the products or services involved.
For expatriates dealing with investments and insurance-based investment products, two regimes are particularly relevant.
An adviser may hold more than one status depending upon the services they provide.
That is why checking the actual permissions shown on ORIAS is more useful than simply asking whether somebody is "regulated".
What is a Conseiller en Investissements Financiers (CIF)?
A CIF is a French regulated status for professionals providing certain forms of financial investment advice.
According to the AMF, a CIF must:
- demonstrate appropriate professional competence
- carry professional indemnity insurance
- belong to an AMF-approved professional association
- be registered with ORIAS
- comply with professional and conduct requirements
The AMF can supervise and sanction CIFs for breaches of their professional obligations.
This provides an important layer of protection for clients receiving investment advice in France.
A useful number: more than 72,000 intermediaries appear on ORIAS
The scale of the French regulatory system is worth understanding.
According to ORIAS, 72,666 intermediaries were registered across insurance, banking, and finance as of 31 December 2025, representing 123,083 registrations across the different regulated categories.
That figure shows why simply finding a business name online is not enough.
You should verify the specific regulatory category and current registration of the professional giving you advice.
How to check whether a financial adviser is regulated in France
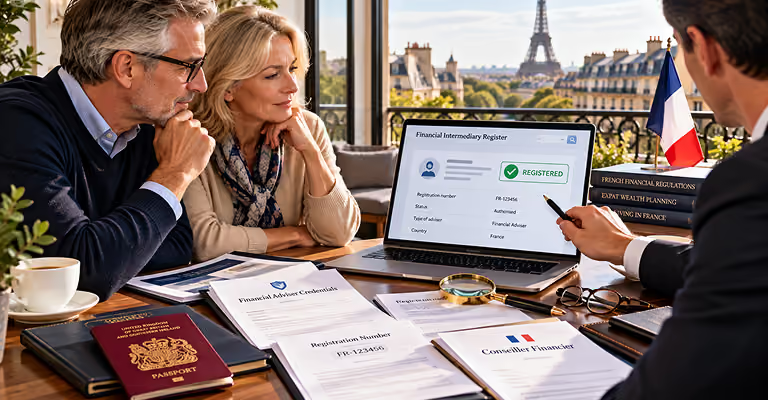
This takes only a few minutes.
Go to the official ORIAS register and search for the adviser's name or company.
For a CIF, the AMF recommends verifying that the register shows the status "INSCRIT" for the relevant authorisation.
You should also check:
- The legal name of the business
- Its ORIAS registration number
- The regulatory categories under which it is registered
- The professional association to which it belongs
- Whether those permissions correspond to the advice or products being offered
One further warning is important.
The AMF has specifically warned consumers about identity theft involving regulated firms. Fraudsters can copy a legitimate business name or use a very similar web address.
Therefore, don't stop at finding a matching name on a register. Compare the company's legal details and contact information carefully.
What should happen before an adviser recommends an investment?
Proper financial advice should involve considerably more than presenting an attractive fund or investment product.
A CIF should first establish enough information to understand your circumstances.
The AMF identifies information including:
- your financial situation
- investment objectives
- investment knowledge and experience
- investment horizon
- tolerance for risk
- ability to absorb losses
This is particularly important for expatriates because tax residence changes the context in which you hold an investment.
An investment that was perfectly reasonable while you lived in Britain may not have the same tax characteristics after you become French resident.
The documents you should expect to receive
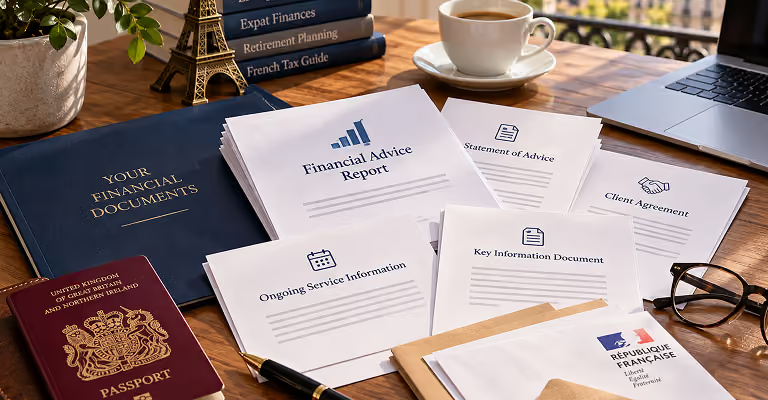
A regulated advice process should leave a paper trail.
At the beginning of the relationship, a CIF should provide documentation identifying the firm, its regulatory status and the professional association to which it belongs.
The adviser should also define the scope of the engagement before providing advice.
Most importantly, the advice itself should be formalised in writing.
The recommendation should explain why the proposed investment is appropriate for your circumstances rather than simply describing why the investment itself is attractive.
That's an important distinction.
Good financial advice isn't simply about whether an investment is good. It is about whether that investment is appropriate for you.
Why this matters particularly for British expats
Cross-border financial planning creates problems that rarely exist when somebody spends their entire working life in one country.
A British resident of France might simultaneously hold:
- a UK State Pension
- one or more UK workplace pensions
- a SIPP
- ISAs
- sterling cash
- UK property
- French property
- an Assurance-Vie
- euro-denominated investments
Each asset can interact differently with French taxation, UK taxation, currency exposure, estate planning and investment regulation.
The objective should therefore not be to optimise each product independently.
It should be to make the whole financial structure work together after the move to France.
UK pensions: SIPP, QROPS or leave the pension where it is?
Pensions are often among the largest assets owned by British expatriates.
But moving to France does not automatically mean you should transfer your UK pension.
Depending on your pension and circumstances, possible strategies include retaining your existing UK pension, consolidating pensions, or considering alternative structures.
QROPS were historically marketed extensively to British expatriates, but the rules governing overseas pension transfers have changed considerably.
The right decision depends on factors such as the pension type, transfer value, residency, tax position, investment requirements, and long-term plans.
A transfer should therefore solve a genuine planning problem, not simply be made because somebody has moved abroad.
Assurance-Vie and French tax residency
Assurance-Vie is another structure British expatriates quickly encounter after moving to France.
Despite the name, it is not simply conventional life insurance. France widely uses the product as an investment and estate-planning wrapper.
Potential advantages can include tax-efficient investment growth, flexibility over withdrawals, and estate-planning benefits, depending on the individual's circumstances and how the contract is structured.
For somebody arriving from Britain, the more useful question isn't:
"Is an Assurance-Vie better than an ISA?"
The two structures belong to different tax systems.
The better question is:
"Which investment structures make sense now that I am tax resident in France?"
What fees should a financial adviser disclose?
Costs matter because they compound the same way as investment returns—except in the wrong direction.
Before investing, ask for the total cost of ownership, not simply the adviser's headline fee.
Potential charges can include:
- initial advice or implementation fees
- ongoing advice fees
- investment fund charges
- platform or custody fees
- insurance-wrapper charges
- transaction costs
- performance fees
- commissions or retrocessions where applicable
- surrender or early-exit penalties
MiFID II and IDD introduced substantial cost and disclosure requirements intended to make these layers more visible to investors.
A 1% difference in annual costs can look insignificant on paper.
It isn't.
For example, £500,000 growing at a hypothetical 5% a year for 20 years would become approximately £1.33 million before costs.
At a net return of 4%, it would become approximately £1.10 million.
That's a difference of roughly £230,000 over the period.
This is only a mathematical illustration — real investment returns fluctuate — but it demonstrates why apparently small annual charges deserve serious attention.
As Benjamin Franklin is often quoted as saying:
"Beware of little expenses. A small leak will sink a great ship."
The same principle applies remarkably well to long-term investment charges.
Red flags when choosing an adviser
Regulation is important, but registration alone doesn't tell you whether an adviser is right for you.
Be cautious where:
- the adviser cannot clearly explain their French or EU regulatory status
- the ORIAS registration cannot be independently verified
- the conversation begins with a product rather than your circumstances
- a pension transfer is presented as the obvious solution simply because you moved abroad
- charges are difficult to understand
- there are substantial early surrender penalties
- investment returns are presented as predictable or guaranteed when they are not
- the adviser relies heavily on "reverse solicitation" to explain why French authorisation is unnecessary
- there is no written suitability assessment
- you are pressured to make a decision quickly
The AMF itself warns investors to be cautious when an adviser promises high returns: greater potential return generally comes with a greater risk of loss.
Can AI replace a financial adviser?
AI can already do something genuinely useful for expatriates: explain terminology.
It can help somebody understand what a SIPP is, summarise the concept of Assurance-Vie, compare investment structures or prepare questions before meeting an adviser.
It cannot turn an unregulated recommendation into regulated financial advice.
An AI model does not appear on the ORIAS register, does not carry professional indemnity insurance for your personal recommendation, and is not accountable to the AMF for the suitability of an investment it suggests.
There is another problem.
Cross-border financial planning sits precisely where AI systems can struggle most: rapidly changing rules combined with highly individual facts.
Whether a strategy is appropriate can depend upon residency, nationality, pension type, family circumstances, investment objectives and the precise wording of tax treaties and domestic legislation.
Use AI to become a better-informed client.
Don't confuse information retrieval with regulated personalised advice.
Five questions to ask a financial adviser in France
Before appointing somebody to advise on your pensions or investments, ask:
1. Under which French or EU regulatory permissions are you advising me?
Ask for the registration details and verify them independently.
2. Can I find you on ORIAS?
Don't accept a screenshot. Check the live register yourself.
3. How are you paid?
Ask for the total expected costs in both percentages and monetary terms.
4. Why is this recommendation suitable for a French resident?
The answer should cover your circumstances and not merely the qualities of the product.
5. What happens after I invest?
Establish whether ongoing reviews are included and how frequently your financial plan will be revisited.
The bottom line
For British expatriates, moving to France changes the regulatory and tax environment surrounding their wealth.
That doesn't necessarily mean changing every pension or investment.
It does mean reviewing whether the people advising you, and the structures you hold, remain appropriate for your new circumstances.
The simplest starting point is also one of the most important:
Verify the adviser before evaluating the advice.
Check the firm's regulatory status, understand how it is paid, insist on written recommendations, and make sure the adviser understands both sides of the UK-France equation.
At Axis Financial Consultants, we specialise in financial planning for British expatriates and internationally mobile clients living in France, including UK pensions, SIPPs, QROPS and tax-efficient investment structures.
Our advisers provide ongoing cross-border planning and regular reviews designed around the client's changing circumstances.
About Des Cooney
He has worked in the financial services industry for 30 years as a retirement and wealth management specialist.