
For British expats, understanding the difference between the investment itself and the structure through which it is held can be an important part of financial planning. One option worth investigating is an investment held within a qualifying life assurance bond, often referred to in the international financial services industry as a Spanish Compliant Investment Bond.
These structures can offer investment flexibility and potential for tax deferral (subject to Spanish law and the terms of the policy). They are not suitable for all investors, and the tax treatment must be established before any investment.
1. Becoming Spanish tax resident: what changes?
Spain typically taxes its tax residents on their worldwide income in accordance with the relevant legislation and tax treaties. That will mean that income and gains from investments held in the UK or elsewhere may be subject to tax in Spain.
Spanish tax residence is not solely determined by the number of days you spend in the country. Under Spanish rules, you are generally deemed to be a tax resident if you spend more than 183 days in Spain in a calendar year. Other factors may also be relevant, including the location of your main centre of economic interests and certain family circumstances.
The UK has its own Statutory Residence Test. Where an individuals circumstances give rise to a potential conflict between British and Spanish rules, the UK/Spain Double Taxation Agreement may need to be looked at. So don't assume that if you spend less than 183 days in Spain you're automatically going to be a UK tax resident.
What about the 90-day Schengen rule?
Following Brexit, British nationals without the relevant residence rights generally face the Schengen short-stay limit of 90 days in any rolling 180-day period across the Schengen Area. The EU Entry/Exit System now electronically records relevant external border crossings and enables authorities to identify overstays.
This is an immigration rule, not a tax residence rule. You can have Spanish tax obligations without having spent more than 90 days in Spain. Conversely, someone within the Schengen short-stay limit should not assume that they therefore have UK tax residence.
British nationals intending to reside in Spain full time will normally require an appropriate residence authorisation. The non-lucrative residence visa is one option for eligible applicants who can demonstrate adequate financial means and meet the other requirements. The right route, of course, depends on individual circumstances.
2. Why investment structures matter
Becoming Spanish tax resident does not mean every investment will be taxed the same way. The treatment will be determined by the nature of the asset, the structure of the investment, the type of income and the relevant Spanish tax rules.
For instance, interest, dividends, and realised investment gains may be taxed very differently from income arising under a life assurance policy. Some unit-linked life assurance contracts may also be eligible for the regime under Article 14.2(h) of the Spanish Personal Income Tax Law.
The distinction is important. Some unit-linked policies which satisfy the statutory conditions can be taxed under the normal life assurance rules. Others which do not satisfy those conditions may be subject to annual income imputation on the basis of the change in value of the underlying assets.
This is one reason the structure of an investment matters as much as the funds you choose within it.
3. What is a Spanish Compliant Investment Bond?

The term Spanish Compliant Investment Bond is used in the international financial services industry to describe a life assurance investment policy which is structured to meet the relevant Spanish tax requirements.
Its not sufficient for a provider or adviser to simply say that a policy is compliant. The actual policy wording, the investment structures and the relevant statutory conditions have to be examined.
A bond may give you access to a range of investment funds, portfolio management, and the ability to change your investments within the contract. It may also allow for partial withdrawals or full surrender, again subject to the terms of the policy.
The potential advantages can include:
- Tax deferral: qualifying policies may permit the investment growth to accumulate tax free on an annual basis (i.e. without an annual personal income tax charge being payable on that growth) so long as the relevant conditions are met.
- Investment flexibility: policyholders may have access to a range of funds and portfolio strategies.
- Flexible access: partial withdrawals may be a way of supplementing your pension
income or meeting other changing financial requirements. - Long-term planning: the policy may form part of a wider retirement and estate
planning strategy.
These features are not guaranteed to be available on all contracts. The charges, restrictions, investment risks and the policy's tax status will all need to be checked before making a decision.
4. How could the Spanish tax treatment be different?
The difference in value between a qualifying life assurance policy and a non-qualifying unit-linked contract can be considerable.
An investor with an investment portfolio in a unit-linked policy may be required to recognise income annually on the basis of the change in the net asset value of the underlying assets, even if no money has been taken out of the policy, if the contract does not satisfy the relevant Spanish statutory requirements.
Where a policy qualifies for the normal life assurance tax regime, it is possible for the investment growth to accumulate within the contract without an annual personal income tax charge on that growth. Tax is generally only relevant when a taxable benefit or withdrawal occurs, and the exact treatment will depend on the contract and the circumstances.
The distinction is therefore not simply between a foreign policy and a Spanish policy. A policy issued outside Spain may qualify for favourable treatment where the relevant requirements are met, whilst another foreign policy may not.
An illustrative example
Suppose a British retiree invests €150,000 in a unit-linked life assurance policy, and the value of that investment subsequently goes up.
If the policy is subject to annual income imputation, then some of that increase may be taxable in each of the relevant tax years even though no withdrawals have been taken by the investor.
If the policy qualifies for the normal life assurance regime, the investment growth can accumulate within the policy without an annual personal income tax charge on that growth. The tax treatment would then apply at the time of any withdrawals or other policy benefits.
The actual tax outcome cannot be determined from the initial investment and the annual growth rate alone. It will depend on the policy terms, the premiums paid, the contract value, the nature and timing of any withdrawals, the relevant tax rules and the investor's own circumstances.
A numerical comparison should therefore be based on sound assumptions and a calculation checked by a Spanish tax specialist.
5. How are withdrawals taxed?
A qualifying bond is not a tax free investment. Tax deferral is not the same as tax exemption.
When a policyholder makes a partial withdrawal, the amount subject to tax may be determined under the Spanish rules for life assurance income. The taxable amount is not necessarily the whole withdrawal, nor can it automatically be assumed to consist only of the investment gain attributable to that particular withdrawal.
The calculation can depend on the policy's value, premiums paid, previous withdrawals and the applicable tax rules. Full surrender may produce a different result from a partial withdrawal.
For retirees using a bond as a source of pension income, the timing and amount of the withdrawals will of course need to be considered in the light of other income, anticipated expenditure and the tax position for that year.
A flexible withdrawal facility can be useful, but it doesn't guarantee you'll be in any particular tax bracket or achieve any particular tax saving.
6. What about the Modelo 720?
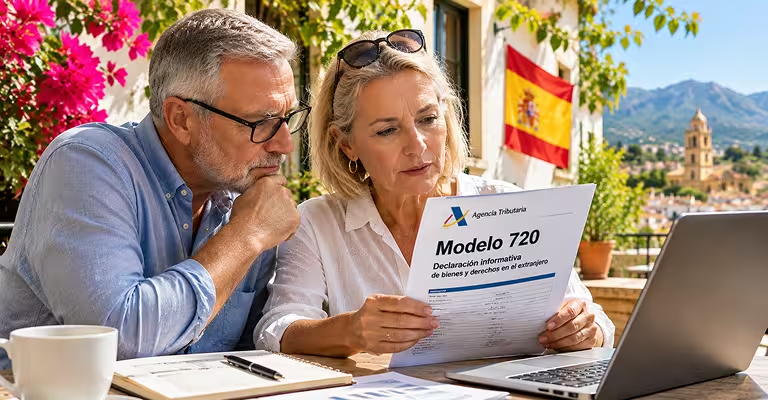
Modelo 720 is an information return relating to specified categories of assets and rights held abroad by certain Spanish tax residents. It is not a general annual declaration that automatically applies to every foreign investment.
Whether a particular account, investment or insurance policy must be reported depends on the relevant reporting category, the applicable thresholds and exemptions, and the individual's circumstances.
Some foreign life assurance rights may fall within the reporting rules. Therefore, do not assume a policy is exempt from Modelo 720 merely because it qualifies for a particular income tax treatment. The Spanish tax authority's guidance should be consulted for the specific asset and reporting period.
Investors should also remember that income tax reporting and foreign-asset information reporting are separate matters. An investment may have no annual personal income tax charge on its growth while still being subject to another reporting or wealth tax obligation.
7. What about UK ISAs and other overseas investments?
UK Individual Savings Accounts (ISAs) are tax-advantaged under UK domestic rules. However, Spain does not automatically recognise their UK tax treatment.
Once an individual becomes Spanish tax resident, income and gains arising from an ISA may be subject to Spanish tax under the rules applicable to the underlying investments. The precise treatment depends on the assets held and the circumstances.
You should also review other overseas investments, including direct shareholdings, funds, deposit accounts, and life assurance policies, on an individual basis. Spanish tax residence can bring worldwide income within the scope of Spanish taxation, but the calculation and timing of tax depend on the type of asset and the applicable rules.
This is particularly important for retirees who have accumulated investments over many years and plan to draw on them to fund their lifestyle in Spain.
8. Questions to discuss with your financial adviser
Moving to Spain is a good opportunity to assess whether your current arrangements still suit you. Before you make any changes, you should consider the following questions with an appropriately qualified and authorised adviser:
Pensions
- Can you continue to access the services and benefits offered by your UK defined
contribution pension provider as a non-UK resident? - Do you intend to take withdrawals, purchase an annuity, or draw a regular retirement
income? - How will pension withdrawals interact with your other income and your overall
Spanish tax position?
Investments
- How will your existing investments be taxed once you become a Spanish tax resident?
- Are your investments still appropriate in the light of your objectives, your time
horizon and your attitude to risk? - Will currency movements have any impact on your retirement spending or on the
value of your investments? - Are you relying on UK tax advantages which may not be recognised in Spain?
Investment bonds
- Does the policy satisfy the relevant Spanish statutory requirements?
- What are the total policy, investment and advice charges?
- How are partial withdrawals and full surrender treated?
- Can the policy be retained if you move to another country, and what would be the tax
implications?
Advice and ongoing support
- Is your current adviser authorised to provide you with the relevant services whilst you're resident in Spain?
- Have your tax position, investment strategy and retirement income needs all been taken into account?
These questions can help you to identify areas which may need further investigation prior to making any major financial decisions.
9. Could a Spanish Compliant Investment Bond form part of your retirement plan?
For some British expats, a qualifying life assurance bond can be a useful vehicle for holding investments and planning future withdrawals. The potential for tax deferral, investment choice, and flexibility may suit those looking to supplement their pension income over time.
However, a bond is not automatically the most suitable solution. It carries investment risk and may entail charges, restrictions and tax consequences that differ from those of other investment structures. It should be compared with the alternatives available to the individual, taking account of their circumstances and objectives.
The real issue isn't whether Spain is a high- or low-tax country. It's how the tax rules apply to your income, assets and investment vehicles, and whether your financial plan remains appropriate once you've relocated.
Conclusion
Moving to Spain can significantly affect pensions, savings, and investments accumulated in the UK. Understanding Spanish tax residence, how overseas investments are taxed, and the difference between qualifying and non-qualifying life assurance policies can help you ask better questions and make informed decisions.
A Spanish Compliant Investment Bond may be worth considering as part of a broader retirement strategy, but the policy's tax status and suitability must be established before investing.
Axis Financial Consultants works with internationally mobile clients who need to consider their investments in the context of cross-border retirement and financial planning. Before changing your arrangements, seek advice from authorised financial professionals and a Spanish tax specialist who can assess your individual circumstances.
Important information: This article is for general educational purposes only and does not constitute personal investment, legal or tax advice. Spanish tax legislation and individual circumstances may affect the outcome. The treatment of any investment bond should be confirmed against current legislation and the specific policy terms before any decision is made.
About Des Cooney
He has worked in the financial services industry for 30 years as a retirement and wealth management specialist.